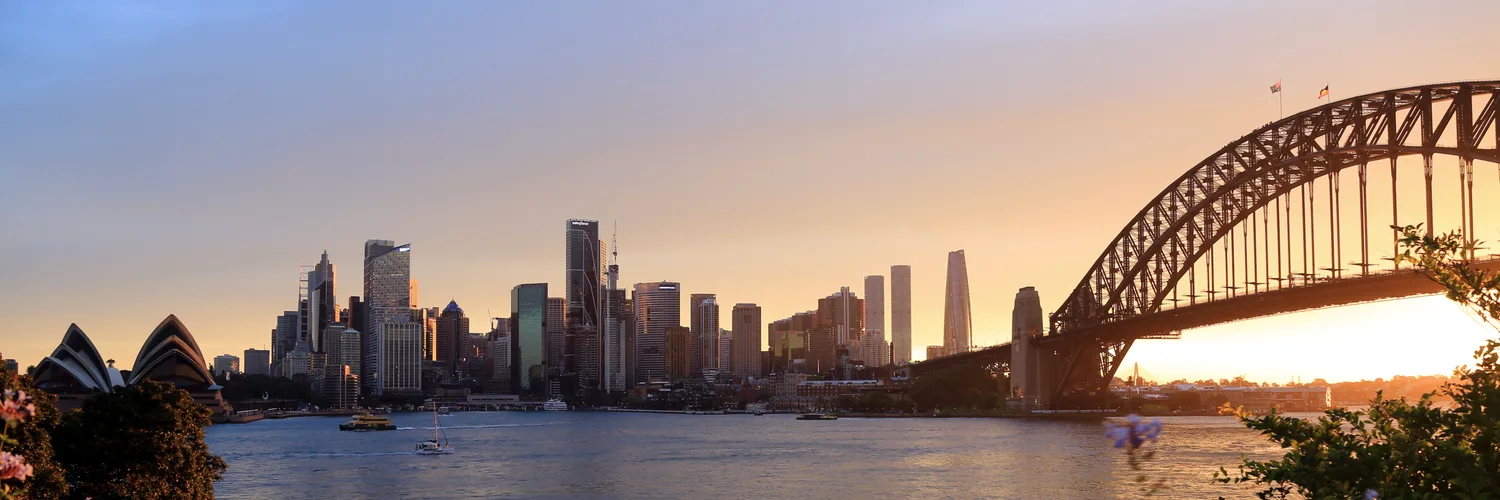
Western Sydney International Airport opens to passengers on 25 October 2026. The $2.1 billion toll-free M12 Motorway that feeds it opened on 14 March 2026. The M7-M12 interchange followed in June.
Sydney’s median dwelling value is $1,222,718, and the market is falling. Values dropped 1.4% in August, 4.7% over the quarter and 4.6% across the year, on Cotality’s Home Value Index to 31 August 2026.
The falls have not been even. Cotality says higher-value housing is still recording larger declines than lower-priced housing. The gap has narrowed, though. Lower-quartile values are now falling too. Looking further out, the new airport, motorway and metro in western and southwestern Sydney will change how these suburbs connect to jobs.
Why western Sydney, why now
Sydney’s median house value sits just under $1.5 million ($1,494,878 at 31 August 2026). That number puts many investors off. But it’s a citywide median pulled up by the eastern suburbs, north shore and inner west.
At the lower-priced end, the picture looks different. In most capitals, lower-priced housing has held up better than the premium end through this downturn. Sydney is one of them.
Western and southwestern Sydney are where the fundamentals line up for investors:
- Infrastructure spend: Western Sydney International Airport (Nancy-Bird Walton) opens to passengers on 25 October 2026. Jetstar flies from day one, Air New Zealand from 26 October and Qantas from 28 March 2027. The M12 Motorway opened toll-free on 14 March 2026. The Western Sydney Aerotropolis is expected to create 200,000 jobs.
- Population pressure: Greater Sydney grew by about 75,200 people in the year to 30 June 2025 (ABS estimated resident population).
- Vacancy: Sydney-wide vacancy sits at 1.71% (SQM Research, August 2026). It has risen from 1.38% a year earlier, so the rental market has loosened a little.
Growth won’t be evenly distributed. Over the year to 31 August, Cotality had its Penrith region (SA3) up 3.8% and its Campbelltown region (SA3) up 2.1%. Sydney as a whole fell 4.6% over the same period.
For a deeper look at how growth and yield work together in a portfolio, see our guide to capital growth vs rental yield.
What matters in Sydney right now
Sydney has the lowest yields of any capital, 3.3% on dwellings and 2.9% on houses (Cotality). Houses on this list yield between 2.49% and 3.47% gross. Sydney is a growth market, and yield comes second. If you need cash-flow neutral from day one, other capitals will get you there faster.
But your portfolio may need a growth asset in the path of the new airport, the M12 and the airport metro. If so, these nine suburbs across two corridors are where the fundamentals stack up. Each one was picked on median price, gross yield, vacancy, infrastructure pipeline and employment diversity. A low-priced suburb with no employment base and no infrastructure pipeline is priced that way for a reason.
We focus on established houses on decent blocks, leaving aside new builds and house-and-land packages on the fringe. Older properties give you more levers. There’s reno potential, the option of a granny flat and no developer margin baked in.
Airds
Median house price: $922,500 Gross rental yield (houses): 3.21% Median weekly rent: $570 12-month growth: +19.57%
Airds has the lowest house median on this list at $922,500. It also recorded the second-fastest growth, 19.57% over the year to June. Its computed yield of 3.21% is third on the list, behind Werrington and Leumeah.
Sales are thin. Only 50 houses sold in the 12 months to June. A handful of sales can move the median a long way. Check recent comparable sales street by street before reading too much into the growth figure.
The risk is perception. Airds has historically sat lower on the desirability scale. The growth over the past year suggests buyers are starting to look past that reputation.
Leumeah
Median house price: $988,500 Gross rental yield (houses): 3.26% Median weekly rent: $620 12-month growth: +9.83% Rent growth (12 months): +6.4%
Leumeah sits right next to Campbelltown CBD. It gets the same infrastructure spending without the higher price tag. It has its own train station on the T8 Airport & South Line. Campbelltown Hospital and the Macarthur Square retail precinct are both close by.
At $988,500, Leumeah is $30,000 lower-priced than Campbelltown proper. Its 9.83% price growth is level with Campbelltown’s 9.81%. The median house rent rose 6.4% over the year to August, from $582.50 to $620 a week. That puts Leumeah’s yield at 3.26%, the second-highest on this list.
If you want to buy in the Campbelltown corridor for less, Leumeah has the same fundamentals for $30,000 under Campbelltown’s median.
Campbelltown
Median house price: $1,018,500 Gross rental yield (houses): 3.17% Median weekly rent: $620 12-month growth: +9.81%
Campbelltown is the main centre of the Macarthur region. The NSW Government invested $632 million in the Stage 2 hospital redevelopment, which is now complete. It added a new clinical services building and an expanded emergency department, plus birthing suites and a maternity ward. It also brought new mental health units and more cancer services.
At $1,018,500, Campbelltown is the anchor pick for the southwestern corridor. That is the suburb median. Across the whole Campbelltown council area, the NSW DCJ median house price is $1,060,000 (March quarter 2026).
The computed yield is 3.17%. Health precinct employment and the train station on the T8 line give Campbelltown a long-term demand base that most outer suburbs don’t have.
Ingleburn
Median house price: $1,080,000 Gross rental yield (houses): 3.13% Median weekly rent: $650 12-month growth: +10.66%
Ingleburn is the employment anchor of the southwestern corridor. The Ingleburn industrial area is a large industrial and logistics precinct. Its local jobs reduce the suburb’s dependence on CBD commuting.
Ingleburn’s computed house yield is 3.13%. That sits just under the 3.19% for houses across the whole Campbelltown council area (NSW DCJ). It is above Sydney’s 2.9% house average (Cotality). For a Sydney suburb with a train station and a diversified employment base, that’s a workable number.
At $1,080,000, Ingleburn is the highest-priced of the four southwestern suburbs. The entry point is higher. In return, the industrial precinct gives tenants local jobs, so demand relies less on the CBD commute. Houses averaged 20 days on market, with 182 house sales in the 12 months to June.
Rooty Hill
Median house price: $1,107,500 Gross rental yield (houses): 3.05% Median weekly rent: $650 12-month growth: +10.75%
Rooty Hill sits in the western airport corridor. The M12 Motorway opened toll-free on 14 March 2026, and the M7-M12 interchange that links it to the M7 opened in June 2026.
At $1,107,500, Rooty Hill sits between Mount Druitt ($1,072,500) and Kingswood ($1,125,000) on price. Values rose 10.75% over the year to June. Over the June quarter they were flat. Houses took 28 days to sell on average, the slowest on this list alongside Mount Druitt.
The Eastern Creek employment zone (home to Sydney Motorsport Park, DFO and a major logistics precinct) sits immediately to the south. Airport access, motorway links, employment diversity and a station on the T1 Western Line give Rooty Hill a solid base of fundamentals.
Mount Druitt
Median house price: $1,072,500 Gross rental yield (houses): 3.04% Median weekly rent: $628 12-month growth: +7.25% Vacancy (postcode 2770): 0.65%
Mount Druitt has benefited from the same western Sydney infrastructure pipeline that’s lifting the corridor. Vacancy tells you more than price growth here. SQM Research had postcode 2770 at 0.65% in August 2026, against 1.71% for Sydney.
At $1,072,500, Mount Druitt has crossed the million-dollar mark. Its 7.25% growth over the year to June is the slowest on this list. Cotality’s Mount Druitt region (SA3) was up just 1.0% in the year to August.
In Mount Druitt, the tight rental market is the key indicator. The long-term fundamentals (airport, motorway, population growth) are sound. Focus on the established pockets with larger blocks rather than the newer subdivisions.
St Marys
Median house price: $1,200,000 Gross rental yield (houses): 2.49% Median weekly rent: $575 12-month growth: +16.67%
St Marys is the gateway to the Western Sydney Airport. The Sydney Metro Western Sydney Airport line will run from St Marys to the airport and Bradfield. Tunnelling finished in March 2026. The line is still under construction. When it opens, St Marys becomes the interchange between the existing T1 Western Line and the new metro.
That interchange is what sets St Marys apart on this list. The suburb becomes a dual-line transport node. Bayswater in Perth is a similar case, where METRONET made it the junction of the Midland and Ellenbrook lines. Transport interchanges attract commercial development, retail and higher-density housing. All of that drives long-term demand.
At $1,200,000 with a yield of 2.49%, St Marys is the highest-priced and lowest-yielding suburb on this list. The cash flow numbers are tight, so this is a growth-first investment.
House values rose 16.67% over the year to June. Momentum has slowed since. Cotality’s St Marys region (SA3) was up only 0.8% in the year to August.
Kingswood
Median house price: $1,125,000 Gross rental yield (houses): 2.70% Median weekly rent: $585 12-month growth: +20.97%
Kingswood anchors the Penrith health and education corridor. Nepean Hospital is a major tertiary referral centre. Western Sydney University’s Kingswood campus adds a second institutional employer and a steady tenant base of students and staff.
At $1,125,000, Kingswood now sits level with Penrith’s $1,120,000 median. Its 20.97% growth over the year to June is the fastest on this list. Houses averaged 18 days on market.
The yield at 2.70% is below Sydney’s 2.9% house average. But the hospital and university give Kingswood a demand floor that purely residential suburbs lack. Health precincts tend to be steady employment anchors. That matters when you’re holding an asset for 10-15 years.
Werrington
Median house price: $1,125,000 Gross rental yield (houses): 3.47% Median weekly rent: $750 12-month growth: +9.22%
Werrington has the highest computed house yield on this list. At 3.47% gross, it sits more than three-quarters of a point above Kingswood and St Marys. The rent is higher ($750 per week) relative to the median. That’s what drives the yield premium.
Western Sydney University’s Penrith campus is nearby. The suburb has a train station on the T1 Western Line. The university, the transport links and the wider Penrith corridor growth story drove 9.22% growth over the year to June.
At $1,125,000, Werrington costs the same as Kingswood but yields 3.47% against 2.70%. That makes the holding cost equation more manageable than Kingswood or St Marys. Sales are thin, at 51 houses in 12 months. For investors who need the numbers to work a bit harder from day one, Werrington has the best rent-to-price ratio in the Penrith corridor.
The quick comparison
| Suburb | Median price | Yield | 12m growth | Key driver |
|---|---|---|---|---|
| Airds | $922,500 | 3.21% | +19.57% | Lowest median, thin sales |
| Leumeah | $988,500 | 3.26% | +9.83% | Campbelltown adjacent, 6.4% rent growth |
| Campbelltown | $1,018,500 | 3.17% | +9.81% | $632M hospital redevelopment |
| Mt Druitt | $1,072,500 | 3.04% | +7.25% | Tight rental market (0.65% vacancy) |
| Ingleburn | $1,080,000 | 3.13% | +10.66% | Industrial employment |
| Rooty Hill | $1,107,500 | 3.05% | +10.75% | Airport corridor, motorway access |
| Kingswood | $1,125,000 | 2.70% | +20.97% | Nepean Hospital, university |
| Werrington | $1,125,000 | 3.47% | +9.22% | Best yield, university corridor |
| St Marys | $1,200,000 | 2.49% | +16.67% | Airport metro interchange |
How the two corridors compare
The spread on this list runs from $922,500 (Airds) to $1,200,000 (St Marys). Every suburb sits below Sydney’s $1,494,878 median house value. That puts them all at the lower-priced end of the city.
The southwestern corridor (Airds, Leumeah, Campbelltown, Ingleburn) is an employment-driven play. The Campbelltown Hospital redevelopment and the industrial precincts provide demand that doesn’t depend on a single project. House yields there are the most consistent on this list, 3.13% to 3.26%.
The western corridor (Rooty Hill, Mount Druitt, St Marys, Kingswood, Werrington) is driven by infrastructure. The Western Sydney Airport, M12 Motorway, Aerotropolis and the airport metro line will shape this part of Sydney for decades. On its own, the Aerotropolis is expected to create 200,000 jobs. Yields there run wider, from 2.49% in St Marys to 3.47% in Werrington.
Growth has slowed across the west. The suburb figures to June show strong annual gains. Cotality’s regions to August are more modest, from 0.8% (St Marys) to 3.8% (Penrith), while Sydney overall is down 4.6%. Sydney houses as a whole yield 2.9%. Most of these suburbs pay only a little above the city average.
The M12 is open, the airport opens in October and the metro is under construction.
No single suburb on this list is the “right” one for every investor. It depends on your budget and your existing portfolio mix. It also depends on whether you’re prioritising yield or growth right now. If you’re buying interstate into NSW, street-level knowledge matters. A buyers agent in Sydney with that knowledge can steer you to the right pocket of a suburb. See our case studies for how that selection works in practice.
This is general information only and not financial advice. Suburb medians, 12-month growth, sales counts and days on market are CoreLogic figures via Your Investment Property to 30 June 2026, and rents are to 31 August 2026. Yields are computed as weekly rent x 52 / median. Sydney-wide and SA3 region figures are Cotality’s Home Value Index to 31 August 2026. Council-area figures are NSW DCJ Rent and Sales (sales March quarter, rents June quarter 2026). Vacancy is SQM Research for August 2026. Figures refreshed 26 September 2026. Speak to a qualified professional before making investment decisions.
See how we find investment-grade properties for investors.
If you want to discuss which Sydney suburbs suit your budget and strategy, book a free discovery call.