An LMI waiver lets you borrow up to 90% of a property’s value without paying lenders mortgage insurance. For some doctors and dentists, the limit is 95%. On an $800,000 purchase with a 10% deposit, that saves about $17,000.
Banks offer it to professions they see as low risk. Doctors are among the investors we buy for. For them, the waiver changes how much cash each purchase needs. This guide covers who qualifies at each bank, what it saves, and which waivers work on an investment loan.
What is an LMI waiver?
Lenders mortgage insurance protects the bank, not you. Most lenders charge it when you borrow more than 80% of the property’s value. Banks call that share the loan-to-value ratio, or LVR. The premium is a percentage of the whole loan. Our LMI calculator shows what it costs on your numbers.
A waiver means the lender doesn’t charge it. You’re still borrowing above 80%, and you still need to pass the bank’s normal credit and serviceability checks.
LMI waiver for professionals: the list
Find your job below. Each line names the lenders that cover it and the highest LVR without LMI, where the lender publishes one. “The Westpac group” means Westpac, St.George, Bank of Melbourne and BankSA. For an investment loan, St.George, Bank of Melbourne, BankSA, ANZ, People First Bank and CBA’s health package say their waiver can apply. Westpac’s page doesn’t say. ANZ’s waivers need principal and interest repayments, and its 95% tier is for owner-occupier loans. We checked each lender’s own website on 7 October 2026.
- GPs, specialists and hospital doctors: the Westpac group up to 95%, and ANZ up to 95% on an owner-occupier loan. CBA and NAB also cover them, and People First Bank covers them up to 90%. Only the Westpac group and CBA’s health package name interns, residents and registrars.
- Dentists: the Westpac group up to 95%, and ANZ up to 95% on an owner-occupier loan. CBA and NAB also cover them, and People First Bank covers them up to 90%.
- Pharmacists: the Westpac group up to 90% on a $90,000 minimum income, CBA’s health package, NAB, and People First Bank up to 90%. ANZ’s fact sheet lists them as ineligible.
- Physiotherapists, optometrists and chiropractors: the Westpac group up to 90% on a $90,000 minimum income, and NAB. ANZ goes to 90% with no minimum income, including investment loans on principal and interest. People First Bank covers optometrists up to 90%. CBA’s health package excludes physiotherapists.
- Vets: the Westpac group up to 90% on a $90,000 minimum income, CBA’s health package, NAB, and People First Bank up to 90%. ANZ goes to 90% with no minimum income, including investment loans on principal and interest.
- Psychologists: the Westpac group up to 90% on a $90,000 minimum income. CBA’s health package and ANZ’s fact sheet exclude them.
- Registered nurses and midwives: the Westpac group up to 90% on a $90,000 minimum income. People First Bank covers registered nurses up to 90%. CBA’s health package excludes nurses, and ANZ’s fact sheet excludes nurses and midwives.
- Lawyers and accountants: Westpac waives LMI with a 10% deposit for practising lawyers, solicitors and barristers and for qualified accountants, on a $120,000 minimum income. ANZ goes to 90% with no minimum income, including investment loans on principal and interest. NAB covers them too but doesn’t publish a limit. Westpac, ANZ and NAB also accept actuaries and CFA members. ANZ doesn’t list IPA members. CBA says to check with a lending specialist.
- Police and paramedics: People First Bank up to 90%.
- Teachers and engineers: none of the lenders we checked publish a profession-based waiver for them on an investment loan.
We also checked Macquarie, ING, HSBC, AMP Bank, BOQ, Bank Australia, Great Southern Bank and Teachers Mutual Bank, and found no profession-based waiver on their websites. Bankwest mentions an industry professional waiver but doesn’t publish the details.
LMI waivers bank by bank
Lender policies change often. Confirm the details with the lender or a broker before you apply.
| Lender | Max LVR without LMI | Investment loans |
|---|---|---|
| Westpac | 95% for doctors and dentists; 90% for other health workers, accountants and lawyers | Not stated |
| St.George, Bank of Melbourne, BankSA | 95% for doctors and dentists; 90% for other health workers | Can apply |
| CBA | 90% for doctors, lawyers and accountants; health package limit not published | Yes on its health package |
| NAB | Not published | Not stated |
| ANZ | 95% for doctors and dentists (owner-occupier, principal and interest); 90% for lawyers, accountants and some health workers | Yes for the 90% group, principal and interest |
| People First Bank | 90% | Yes |
| ubank (any borrower) | 90% | Check with ubank |
Westpac, St.George, Bank of Melbourne and BankSA
The four banks publish the same health tiers. Dentists, GPs, hospital doctors and medical specialists can borrow up to 95% with no LMI and no minimum income. Other health professionals on a longer list can borrow up to 90% with no LMI on a minimum income of $90,000. That list covers audiologists, chiropractors, midwives, occupational therapists, optometrists, osteopaths, pharmacists, physiotherapists, podiatrists, psychologists, radiographers, registered nurses, sonographers, speech pathologists and vets.
Westpac also waives LMI with a 10% deposit for qualified accountants and practising lawyers. They need a minimum taxable income of $120,000.
St.George, Bank of Melbourne and BankSA say the waiver can apply “whether you’re buying to live in or invest”. Westpac’s healthcare page doesn’t say.
Commonwealth Bank
CBA invites doctors, lawyers and accountants to check with a lending specialist whether they qualify. The deposit can be as little as 10%. It doesn’t publish a list for that offer.
Its separate health package covers GPs, medical specialists, dentists, pharmacists, vets and doctors in training. It excludes physiotherapists, psychologists and nurses. That package waives LMI on high-LVR borrowing for a home loan or an investment home loan.
NAB and ANZ
NAB names 18 medical professions, from anaesthetists and GPs to physiotherapists, pharmacists and vets. It adds accountants, actuaries, financial analysts, barristers, lawyers and solicitors. Medical professionals must be registered with AHPRA. NAB says the waiver depends on profession, loan type and LVR, but doesn’t publish the limits.
ANZ offers its waiver to legal, medical and accounting professions. Its 2024 information sheets, on its website, set two tiers. Doctors, dentists and specialists can borrow up to 95% on an owner-occupier loan with principal and interest repayments. Lawyers, accountants, physiotherapists, chiropractors, optometrists and vets can borrow up to 90% with no minimum income, on an owner-occupier or investment loan with principal and interest repayments. For an interest-only loan, ANZ asks you to check what deposit applies. Its older fact sheet lists nurses, midwives, pharmacists and psychologists as ineligible.
People First Bank and ubank
People First Bank runs two packages with no LMI up to 90%. The Essential Services Package covers registered nurses, qualified paramedics and sworn police officers. The Medical Professional Package covers GPs, hospital doctors, medical specialists, dentists, pharmacists, optometrists and vets. The bank says investors can use either one.
ubank waives LMI with a 10% deposit for any borrower who meets its criteria, whatever their job. Its page is unclear on investment loans, so check before you rely on it.
What an LMI waiver saves
The saving is the premium you would otherwise pay. Our LMI calculator uses indicative rates. On a 90% loan, it puts LMI at about $11,772 on a $600,000 purchase, $17,042 on $800,000 and $22,644 on $1,000,000. At 95%, the premium roughly doubles.
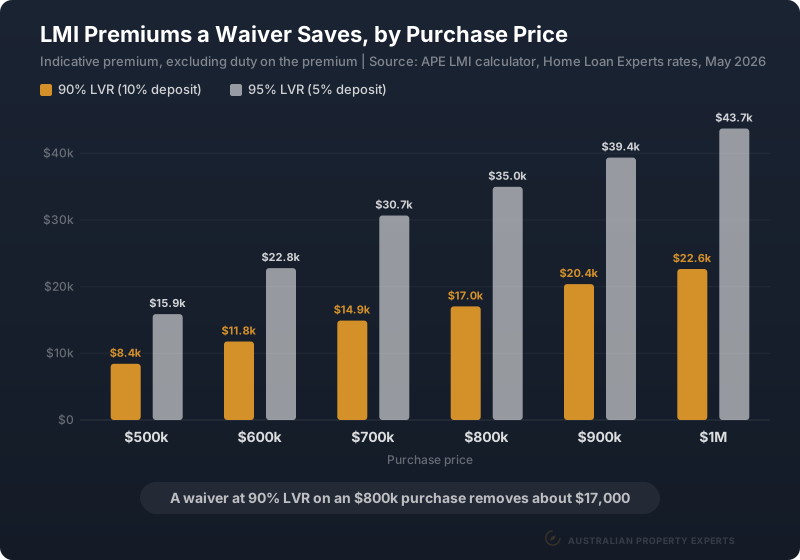
Those figures are before stamp duty on the premium, which several states charge. Premiums also vary between lenders and insurers. Quotes on the same loan can differ a lot. Treat these as a guide and get a quote for your own loan.
LMI waivers on investment loans
If you’re buying an investment property, check first that the waiver covers investment loans. St.George, Bank of Melbourne, BankSA, ANZ, People First Bank and CBA’s health package say theirs can, for some or all of the professions they cover. The other lenders don’t say.
The after-tax saving is smaller for an investor. LMI on an investment loan is generally claimed as a borrowing expense over five years, or the loan term if shorter. Part of the premium would have come back at tax time. Your accountant can work out what that means for you.
Going in at 10% instead of 20% on an $800,000 purchase leaves $80,000 in your account. Stamp duty and buying costs still come on top of the deposit. Our guide to how much deposit you need for an investment property has the total for each state. For a portfolio builder, that $80,000 can be most of the next deposit. Our usable equity calculator shows what you can borrow against once the first property grows.
The smaller deposit also means a bigger loan. You’ll pay more interest too. Check you can hold the property comfortably on the rent and your income.
LMI waivers for nurses and teachers
Registered nurses have two routes. The Westpac group covers them up to 90% on a $90,000 minimum income. People First Bank covers them up to 90% too. Its Essential Services Package also covers sworn police officers and qualified paramedics.
None of the lenders we checked publish a profession-based waiver on an investment loan for teachers or engineers. ubank’s waiver doesn’t depend on your job, so it’s one to ask about. The government’s 5% Deposit Scheme only works for a home you live in, as our 5% Deposit Scheme guide explains.
How to get an LMI waiver
Start with your registration or membership. Lenders such as NAB and Westpac want proof you’re practising. That might be AHPRA registration, a current practising certificate, or membership of CA ANZ, CPA Australia or IPA.
Then check the income floor and the lender’s list for your exact role. The lists differ. A pharmacist qualifies at Westpac and NAB, but ANZ’s fact sheet lists pharmacists as ineligible.
A broker who works with several of these lenders can match you to the right one. If you’re buying an investment, ask them to confirm in writing that the waiver covers an investment loan.
This is general information only and not financial advice. Speak to a qualified professional before making investment decisions.
If you qualify for an LMI waiver and want to put it to work on an investment property, book a free discovery call.