Every investor and their dog has been piling into Brisbane, Perth and Adelaide for the past few years. Fair enough. Over the year to August, Perth values rose 15.6%, Brisbane 10.8% and Adelaide 8.6%. Perth’s ten strongest regions rose between 17.2% and 21.7%. But that’s exactly why Melbourne deserves a closer look right now.
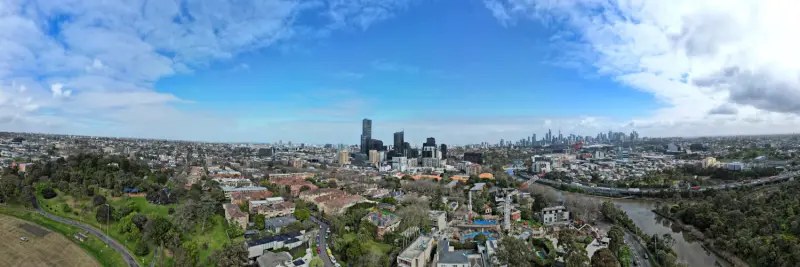
Melbourne’s median dwelling value is $786,718 on Cotality’s Home Value Index to 31 August 2026. It fell 1.1% over the month, 3.9% over the quarter and 4.7% across the year. It sits 6.8% below its March 2022 high and never retook it through the 2024-26 upswing.
The other big capitals all sit above it on the same index: Sydney $1,222,718, Brisbane $1,080,142, Perth $999,987 and Adelaide $937,207. Canberra is higher too, at $864,998. Only Hobart ($752,397) and Darwin ($647,259) come in lower. Melbourne is now the lowest-priced of the five largest capitals, which would have been hard to picture five years ago.
The cycle position argument
Property markets tend to rotate rather than move in sync. Brisbane, Perth and Adelaide have had five years of strong runs, up between 64% and 80% over that stretch. Over ten years, values in all three have more than doubled.
That run has now turned. In August Brisbane fell 1.0%, while Perth and Adelaide each fell 0.8%. On the August index Melbourne is down 4.7% over the year and 3.9% over the quarter. That looks weak next to the annual gains in the mid-sized capitals, and it is exactly why the entry price is where it is.
Victoria is 32% behind its own housing target
Victoria set a target of 800,000 new homes over ten years, roughly 80,000 per year. In 2025, the state completed 54,280 new homes (ABS Building Activity). The result is a 32% shortfall against target in a single year.
It’s getting worse, not better. Completions fell from 60,859 in 2024, and the 2025 total was 12% below the ten-year average. Victoria’s dwelling approvals are running 11% below the 10-year average too.
Cotality points to elevated construction costs, capacity constraints and feasibility problems. Together they limit any material lift in completions. A shortfall this size tends to support prices over the long run, especially while completions keep falling.
Rental market data
Melbourne’s vacancy rate was 1.78% in August 2026 (SQM Research). That’s well below the 3% level considered balanced. It is still looser than Brisbane at 0.87%, Adelaide at 0.64% and Perth at 0.61%.
Gross rental yields across the metro area, on Cotality’s August index:
- Houses: 3.5%
- Units: 5.1%
Cotality’s rent index has Melbourne house rents up 5.1% over the year to August and unit rents up 4.9%. Rents are still rising while values fall, and that combination lifts yields. For investors who need both growth and yield, Melbourne’s unit market at 5.1% gross is worth a close look. Check the growth record first, because a high unit yield can hide years of falling values. Our screen of 153 Melbourne unit markets found nine that pass on price, supply, vacancy and yield.
Population: the demand engine
Greater Melbourne grew by 105,030 people in 2024-25, more than any other capital (ABS). Net overseas migration added 81,168, also the largest intake of any Australian city. Natural increase added another 32,416.
There’s a common objection: “But people are leaving Victoria.” It’s partly true. Greater Melbourne lost a net 8,554 people to internal migration in 2024-25. But that’s small against 81,168 overseas arrivals.
So Melbourne is adding more people while building fewer homes.
Infrastructure beyond the Metro Tunnel
The Metro Tunnel gets most of the attention, but the broader infrastructure pipeline is what changes Melbourne’s long-term growth corridors.
Suburban Rail Loop (SRL East): This connects Cheltenham to Box Hill via six new stations. The state’s funding plan splits it three ways at $11.5 billion each: state, Commonwealth and value capture. Construction started in 2022, and works are under way at all six station sites. The suburbs along this corridor, Clayton, Monash, Glen Waverley, Burwood and Box Hill, will see a real lift in transport access.
Sunshine: The state names Sunshine, with Clayton and Broadmeadows, as a future transport super hub. Regional passengers will be able to change there without travelling through the CBD.
Each of these projects creates a new set of suburbs worth watching. That’s a different growth profile to Brisbane and Perth, where infrastructure spending is concentrated in fewer corridors.
Where the risk sits
Melbourne is not a sure thing, and no market is. A few things could go wrong:
State government debt and taxation. Victoria’s state debt is a real pressure, and recent land tax changes spooked some investors. Further tax changes could dampen sentiment again. Allow for that risk in your numbers.
Economic softness. Real wages have fallen for four consecutive quarters, Cotality notes. If the broader economy doesn’t pick up, the property market will be slow to respond.
Rate sensitivity. Cotality’s August report noted that a growing number of economists expected another RBA rate rise in September or November. A higher cash rate bites hardest on heavily mortgaged households.
Slow recovery, not a boom. Melbourne values were still falling in August, down 1.1% for the month. When the recovery comes it is likely to be gradual. Investors expecting a quick turnaround may be disappointed.
The contrarian case
The best time to buy into a market is usually when everyone else is looking elsewhere, and right now most investors are looking past Melbourne.
The median dwelling value is 6.8% below its 2022 peak. Dwelling approvals are running 11% below the decade average. Vacancy is well under what’s considered balanced. Greater Melbourne added more people than any other capital in 2024-25. And the infrastructure pipeline is creating new growth corridors.
None of this guarantees short-term growth. Some investors are building a portfolio over 10-15 years. For them, Melbourne is worth a look while it sits below its peak and most investors are still focused on Brisbane and Perth.
Want to know which corridors and price points suit your situation in Melbourne? Check out our best suburbs to invest in Melbourne guide or our Melbourne buyers agent page. If you’re buying interstate into Victoria, our case studies show what we’ve bought for clients.
If Melbourne’s yields feel too tight, Geelong’s affordable-market suburbs are often the better entry point for investors prioritising both yield and growth.
This is general information only and not financial advice. Speak to a qualified professional before making investment decisions.
See how we buy investment properties in markets like Melbourne.
Considering Melbourne for your next investment? Book a free discovery call and we’ll walk through the numbers with you.